Consumers in Kenya increasingly discover products on social media, negotiate via WhatsApp and pay through mobile‑money or card links without ever visiting a traditional checkout page.
A Communications Authority survey showed 71.3% of respondents used phones for e‑commerce, compared with 11.7% on laptops and 9.6% on tablets, explaining why merchants are building sales flows around apps and messaging platforms.
WhatsApp now accounts for more than 20% of online shopping orders, according to Mastercard and Flowcart, highlighting the scale of conversational commerce.
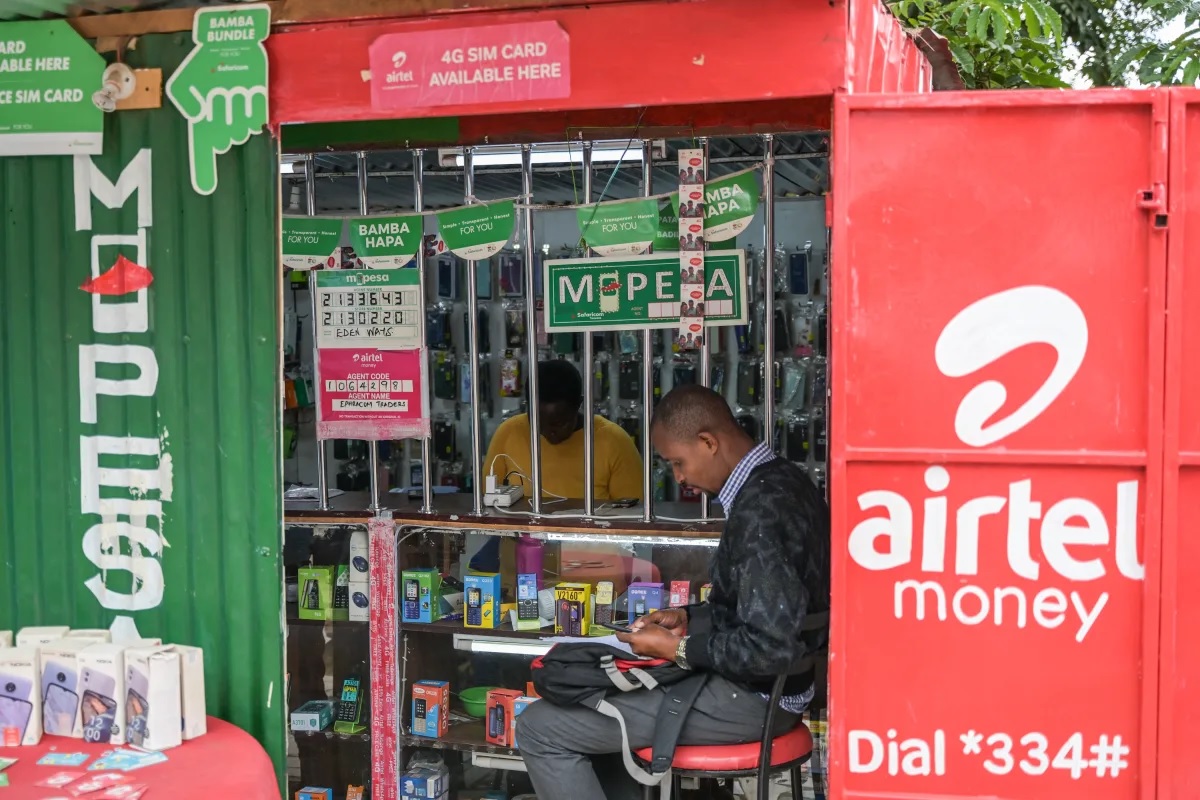
The shift has broadened the payment landscape: mobile‑money remains dominant, but cards, QR codes, bank transfers and digital wallets are also growing, with 13.76 million payment cards in circulation and 94.35 million mobile‑money accounts recorded by the Central Bank of Kenya in July 2026.
Fraud concerns now focus on identity and merchant legitimacy rather than just payment security; 70% of card‑related fraud occurs in card‑not‑present transactions, and 2.3% of Kenyan transaction attempts in 2025 were flagged as suspected digital fraud.
A study cited by TechTrends found that 91% of Kenyan consumers consider data‑privacy a top factor when shopping online, and 80% would avoid a platform after experiencing fraud.
To address these risks, payment networks are deploying tokenisation, contextual fraud intelligence and AI‑driven decision engines that assess device, merchant and behavioural signals before approving a transaction.
Despite stronger back‑end checks, consumers still expect frictionless checkout; repeated password or OTP prompts can cause cart abandonment, so security solutions aim to operate invisibly and intervene only when risk is elevated.
Artificial intelligence adds both convenience and vulnerability: while 89% of Kenyan shoppers have used AI tools during purchase journeys, only 29% trust AI agents to complete checkout, and fraudsters can exploit the same technology to craft convincing scams.
Industry estimates project Kenya’s e‑commerce market could grow from KSh336.7 billion to roughly KSh496 billion by 2029, but that expansion will depend on robust identity verification, fraud detection, clear recourse mechanisms and interoperable payment rails across the region.


Comments