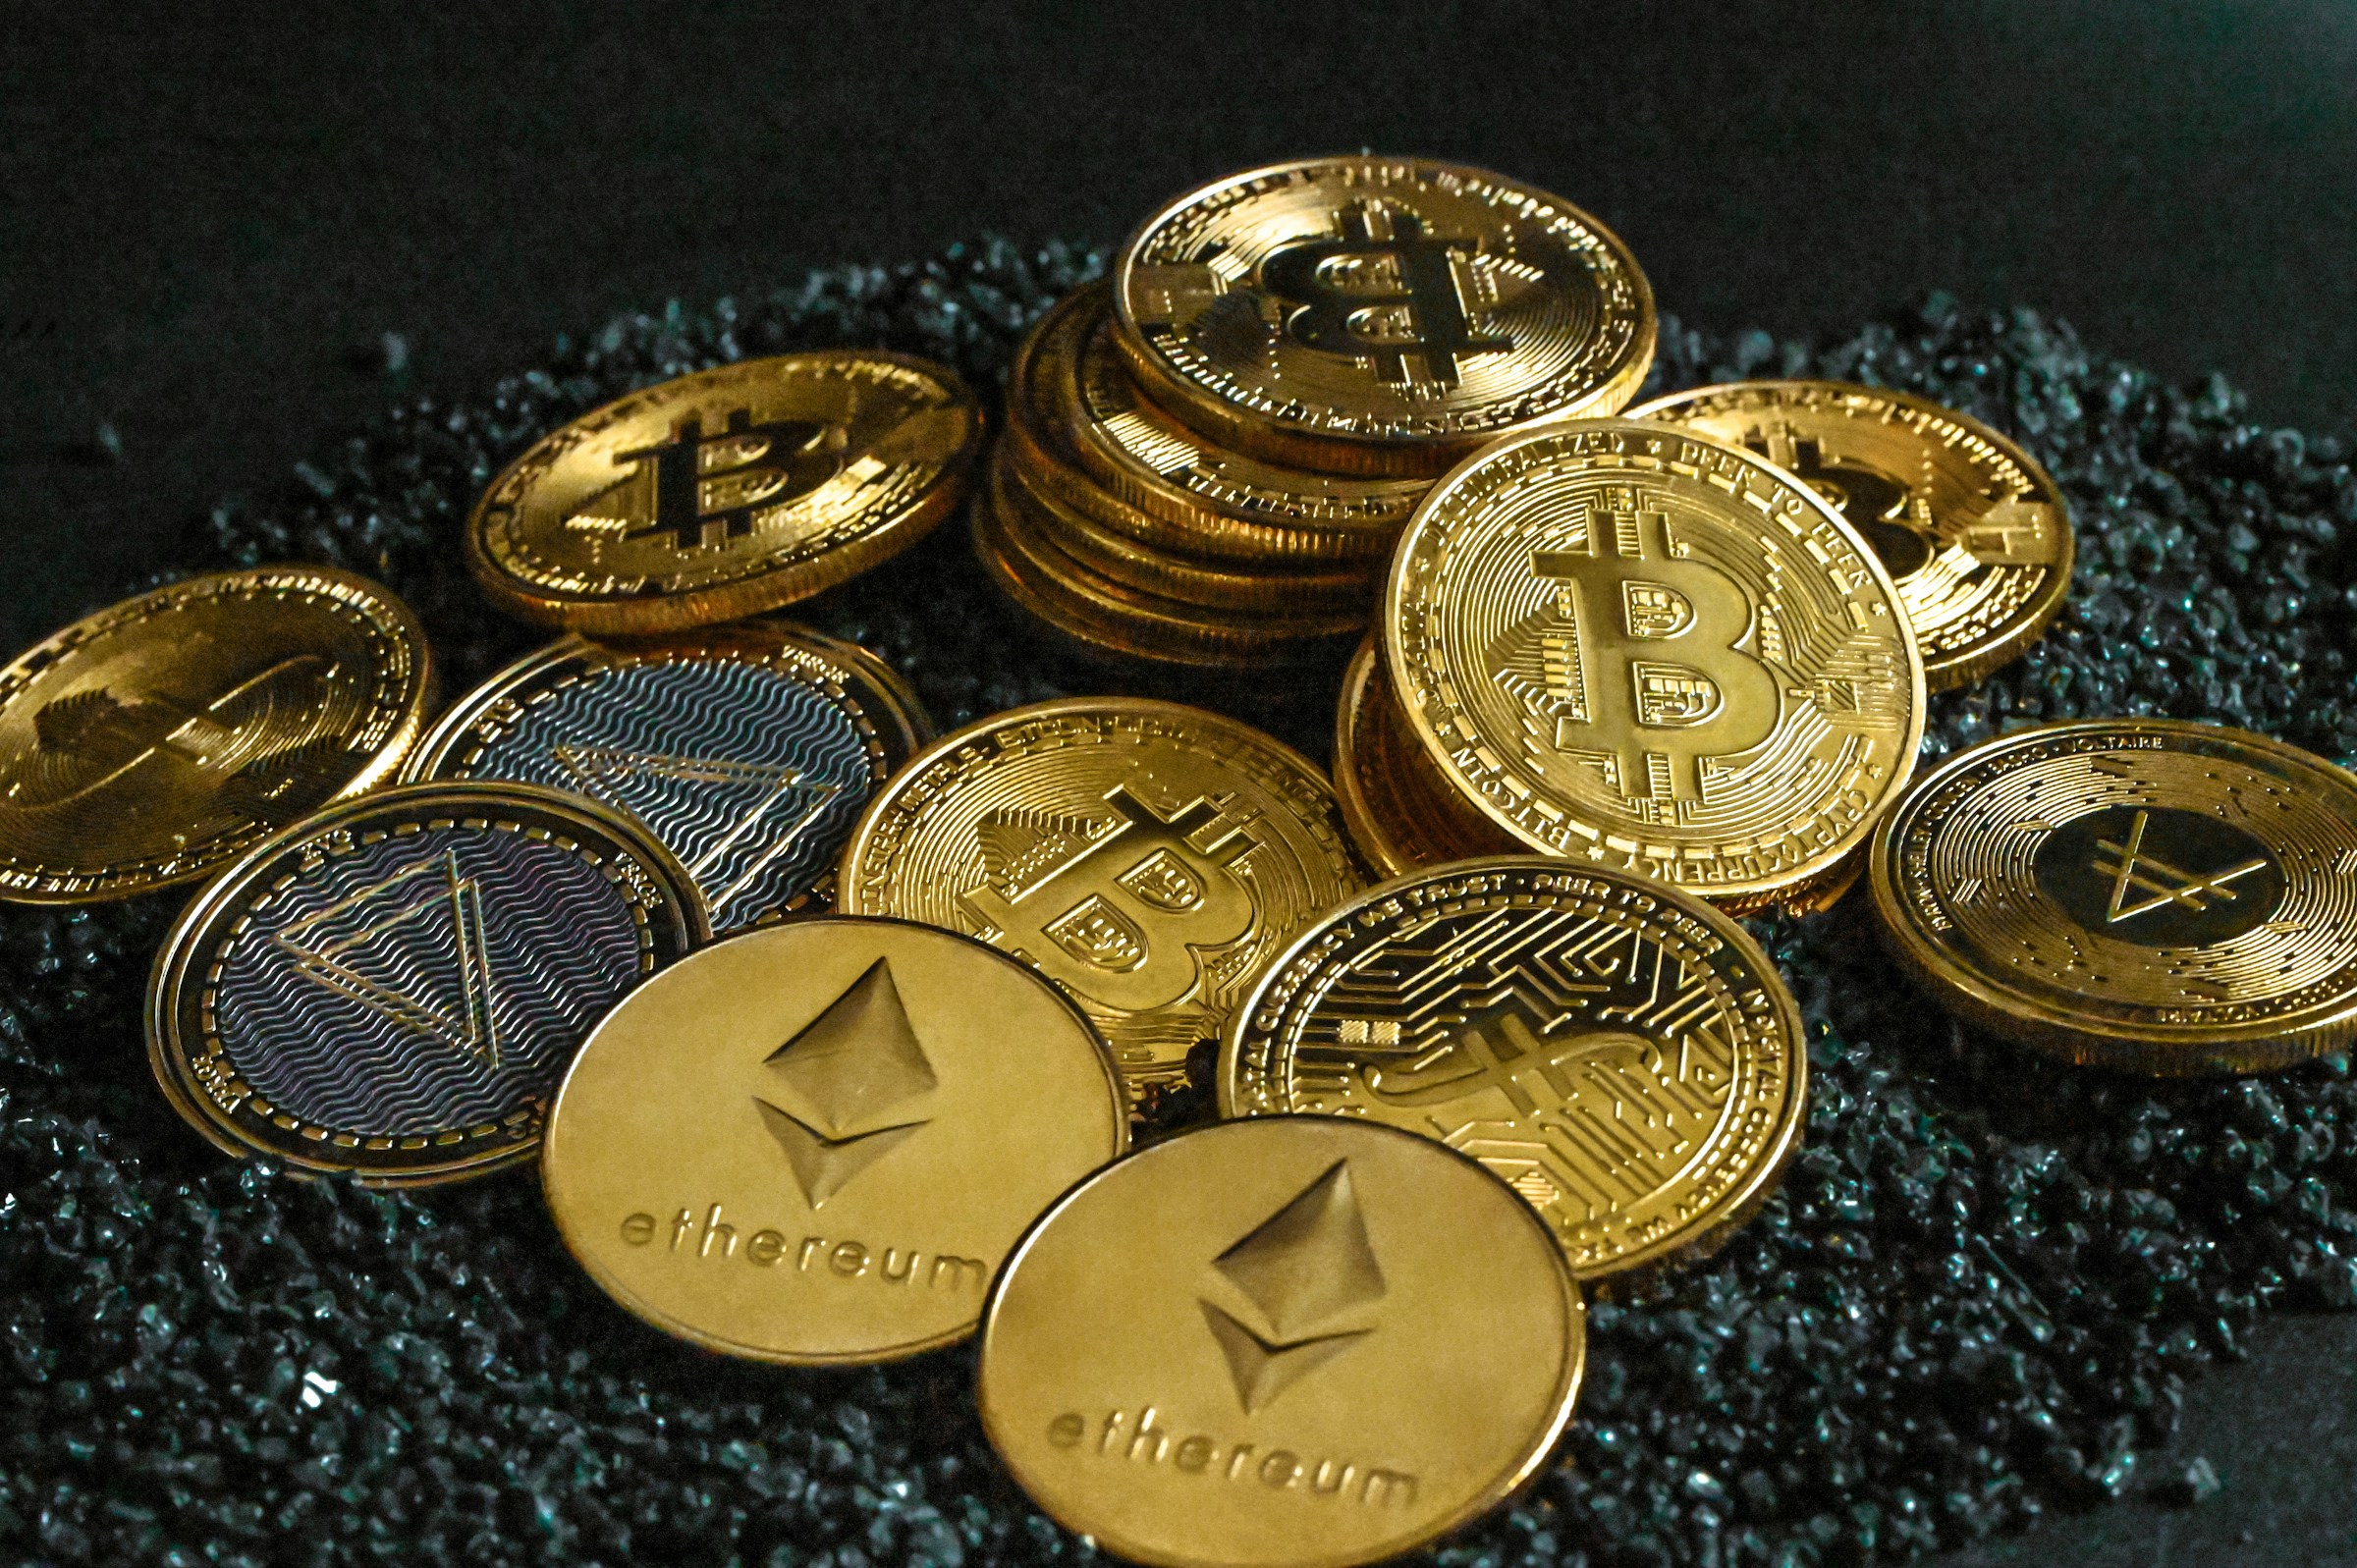
Kenya’s Virtual Asset Service Providers Regulations, 2026 introduce licensing, governance, capital, consumer protection, cybersecurity and anti‑money‑laundering requirements for firms operating in the virtual‑asset market.
Regulatory oversight is split between the Capital Markets Authority and the Central Bank of Kenya, depending on the specific activity, bringing virtual‑asset services closer to the formal financial system.
Stablecoin issuers must obtain approval from the Central Bank, meet reserve and redemption standards, and are barred from paying interest or other remuneration based on holding periods, distinguishing payment‑oriented tokens from deposit‑like products.
The regulations require authorisation for converting virtual assets to or from foreign currency, pulling foreign‑exchange considerations directly into the regulatory scope.
Higher capital and compliance obligations aim to enhance market resilience but may raise entry barriers for smaller Kenyan startups, prompting concerns that larger international operators could dominate the licensed space.
How the rules fit into Kenya’s broader payments ecosystem
The VASP framework arrives as Kenya’s payment system is being rebuilt around interoperability, with banks competing in instant payments, mobile‑money networks becoming more connected, and PesaLink expanding its account‑to‑account infrastructure.
Recent data show 19 banks and micro‑finance institutions adopting a common PesaLink pricing structure, offering free transfers up to KSh1,000 and a flat KSh20 charge thereafter, underscoring the move toward a unified domestic payments layer.
Mobile‑money platforms such as M‑Pesa and Airtel Money are also seeing greater interoperability, allowing customers to transact across competing ecosystems while maintaining distinct market shares.
A partnership between DCSPay and Kotani Pay enables stablecoins to fund payouts that are settled in local currency via established African channels, including mobile‑money and USSD, illustrating a practical model where the blockchain layer sits alongside traditional payment rails.
Potential next steps and industry outlook
If licensed VASPs can secure banking relationships, FX access and payment‑API integrations, they could act as a regulated bridge linking stablecoin liquidity to Kenyan banks, mobile‑money wallets and merchant payment accounts.
Conversely, should these connections remain isolated, the regulations would mainly formalise the existing cryptocurrency market without reshaping Kenya’s broader financial plumbing.
Comments