Each month about 25,000 new customers open an I&M Bank account without a paper form, using only a national ID, a smartphone and a liveness check to verify identity.
Within five minutes the new account is funded through M‑PESA, allowing immediate use of the account.
Digital onboarding now accounts for roughly 85% of the bank’s retail accounts, a shift from its historic focus on corporate‑employee banking.
Why free transfers matter
I&M Bank makes transfers to M‑PESA and Airtel Money free, a policy that diverged from most peers after the COVID‑era fee waiver ended.
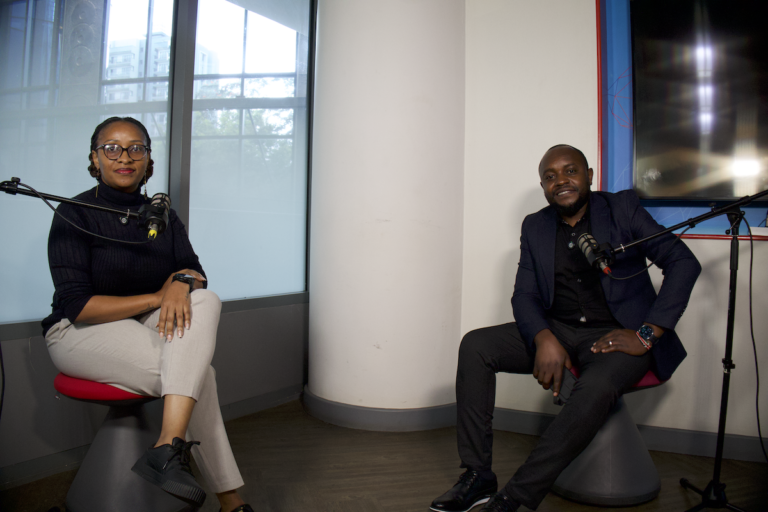
Group Director for Digital Business Eunice Gatåma says the decision reflects the bank’s view of transaction‑cost pain and aims to attract customers who value cost‑free transfers.
Digital short‑term loans and credit scoring
I&M’s app‑based short‑term loan, offered on an opt‑in basis, uses automated credit scoring and has disbursed close to KES 700 million (about USD 5.4 million) in Kenya.
The loan limit grows with responsible repayment and requires no paperwork, targeting “natural hustlers” who need quick access to funds.
Scoring models combine income proxies, credit‑bureau data and in‑app behaviour such as utility bill payments, and 90% of I&M customers are now digitally active, up from 80% a year earlier.
Future focus on ecosystem and data governance
The bank plans to extend the short‑term loan into a working‑capital facility for small traders in newly opened county branches.
I&M runs an enterprise data office that monitors data quality and compliance, requiring fintech partners to meet strict data‑handling standards before integration.
Gatåma says the next growth phase will rely on hyper‑personalisation and partnership‑driven ecosystem leadership rather than competing directly with fintechs.


Comments