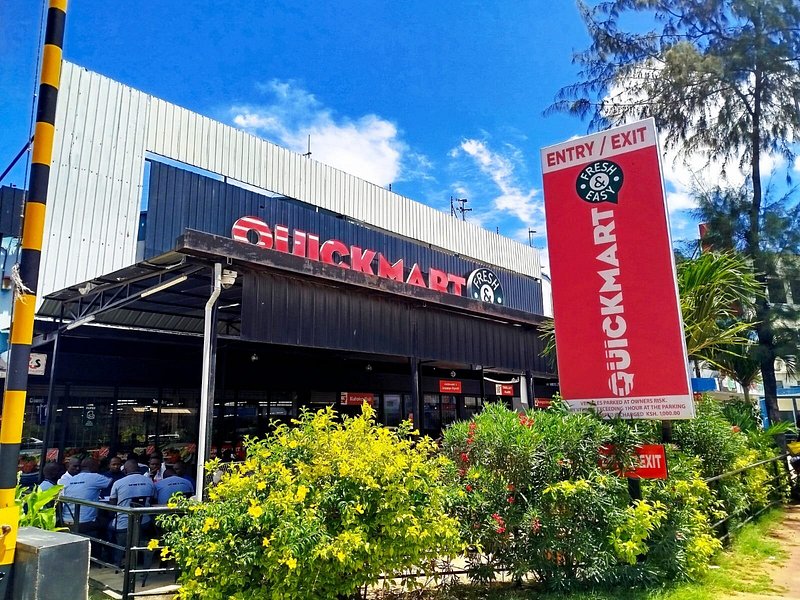
Quickmart disclosed that it ended a series of consultancy and management agreements linked to its founders in July 2026, shortly before the scheduled close of its initial public offering on 30 October.
The terminated contracts covered services such as property sourcing, construction oversight, lease negotiations, supplier engagement and expansion advice, reflecting core activities for the supermarket chain’s growth.
Payments to related‑party service providers totalled KSh638.1 million for FY2025, including KSh208.4 million in management fees to Quickmart’s parent companies and KSh268.7 million to Basic Land Investment Limited for property services.
Additional payments of KSh161 million to Resource Business Investments Limited for expansion advice were recorded in FY2025, with further amounts paid in the first half of 2026.
Despite ending the service agreements, Quickmart continues to lease 18 store locations from entities linked to its founders, the directors or the founder of Tumaini Self Service, asserting that the leases are on arm‑length terms.
The company’s CFO, Simon Macharia, highlighted regular governance practices such as monthly board meetings and weekly executive committee sessions, emphasizing that financial decisions are driven by commercial considerations rather than personal relationships.
Quickmart’s IPO involves the sale of two billion existing shares at KSh7.50 each, valuing the offer at roughly KSh15 billion and implying a total equity valuation of KSh30 billion; proceeds will go to existing shareholders, not as new capital for the company.
For the fiscal year 2025, Quickmart reported revenue of KSh50.4 billion and net profit of about KSh1.5 billion, up from KSh46.7 billion and KSh1.1 billion respectively in FY2024.
The information memorandum acknowledges that related‑party arrangements may give rise to actual or perceived conflicts of interest, but states that no known conflicts would materially affect the offer as of the document’s date.
Investors are advised to consider the disclosed payment figures, the termination of service contracts, and the ongoing related‑party leases when evaluating Quickmart’s IPO prospectus.

Comments