
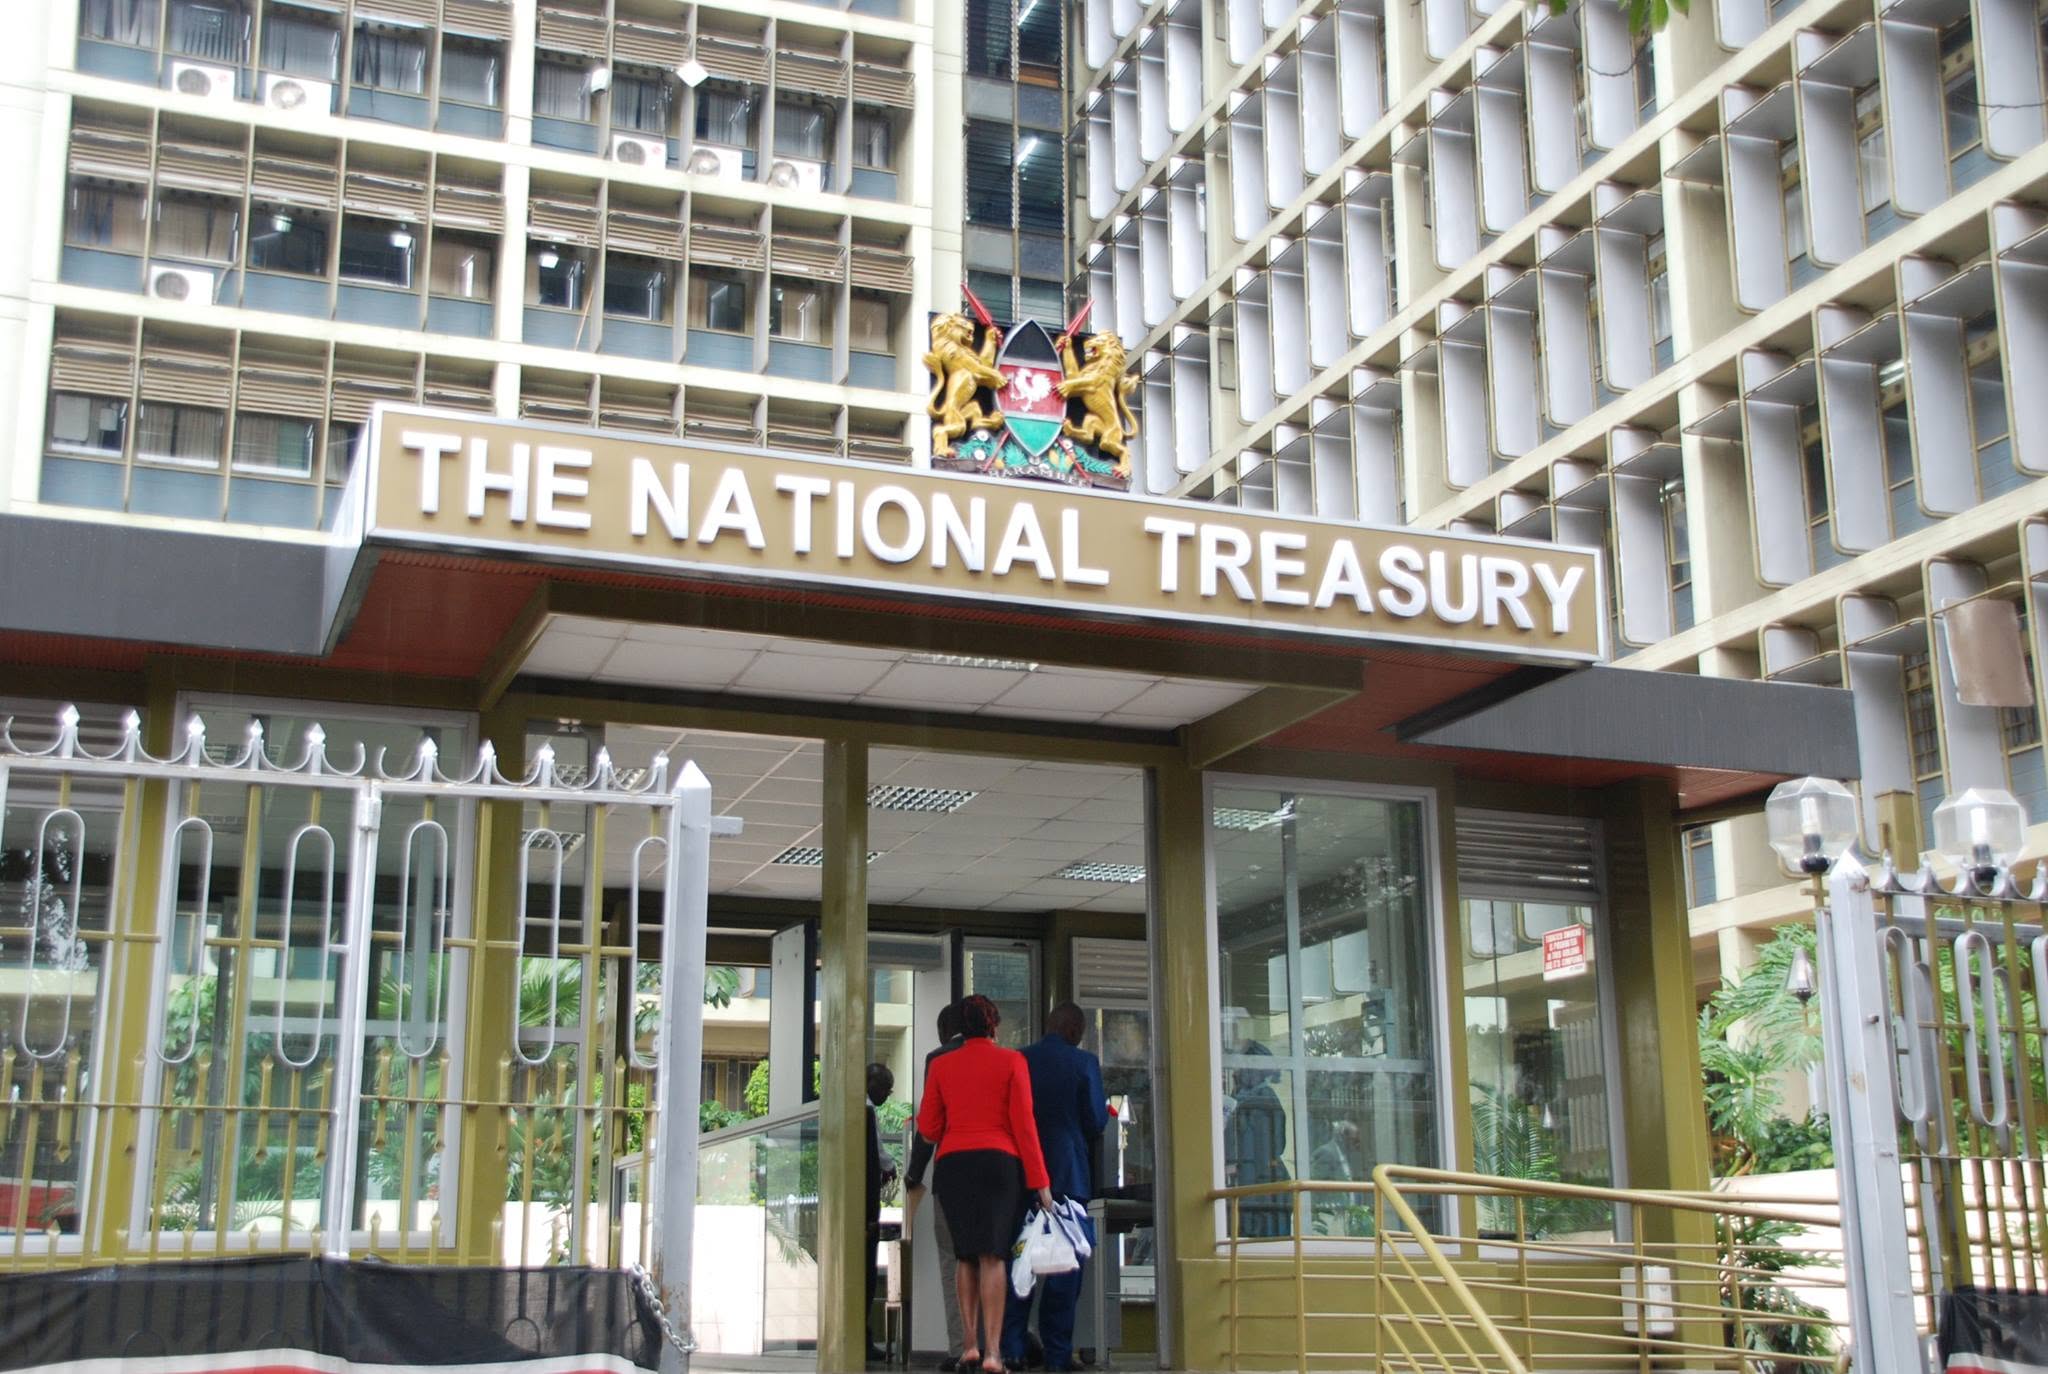
The Kenya Revenue Authority (KRA) has instructed taxpayers covered by the Minimum Top‑Up Tax regime to disclose their corporate ownership structures by 30 November 2026, as part of compliance measures introduced under the Income Tax Act.
In a notice issued on Monday, KRA directed the affected entities, termed “covered persons”, to inform the Commissioner that they fall within the regime and to provide details of their multinational groups.
The required information includes the group name, the country of the ultimate parent, and a list of all Kenyan constituent entities with their respective Personal Identification Numbers (PINs).
KRA specified that the disclosure must be sent to the email address [email protected] before the 30 November deadline.
The notice also reminded covered companies that they must file returns declaring their Minimum Top‑Up Tax liabilities and settle any amounts due under the law.
In addition, affected taxpayers are required to comply with the Multilateral Competent Authority Agreement on the Exchange of GloBE Information, which facilitates sharing data under the global minimum tax framework.
The Minimum Top‑Up Tax was introduced through Section 12G of the Income Tax Act via the Tax Laws (Amendment) Act, 2024, and its enforcement framework is set out in the Income Tax (Minimum Top‑Up Tax) Regulations, 2026 (Legal Notice No 189).
The regime targets large multinational enterprise groups whose ultimate parent’s consolidated annual turnover reaches at least €750 million (about Sh112 billion) in the parent’s financial statements.
A group qualifies if it meets the turnover threshold in at least two of the four financial years preceding the year under assessment, and the tax applies to resident entities and permanent establishments in Kenya belonging to such groups.
Public entities that do not engage in business activities are exempt from the requirement.
The Minimum Top‑Up Tax aims to ensure an effective tax rate of at least 15 percent on profits earned in Kenya, supplementing the standard 30 percent corporate rate where incentives lower the effective rate.
Companies whose effective tax rate falls below 15 percent must pay an additional amount to bridge the gap, aligning Kenya with the OECD’s Global Anti‑Base Erosion (GloBE) Pillar Two framework.
The tax applies to income years starting on or after 1 January 2025, and KRA urged all covered taxpayers to meet the disclosure deadline and seek clarification via [email protected].
Comments