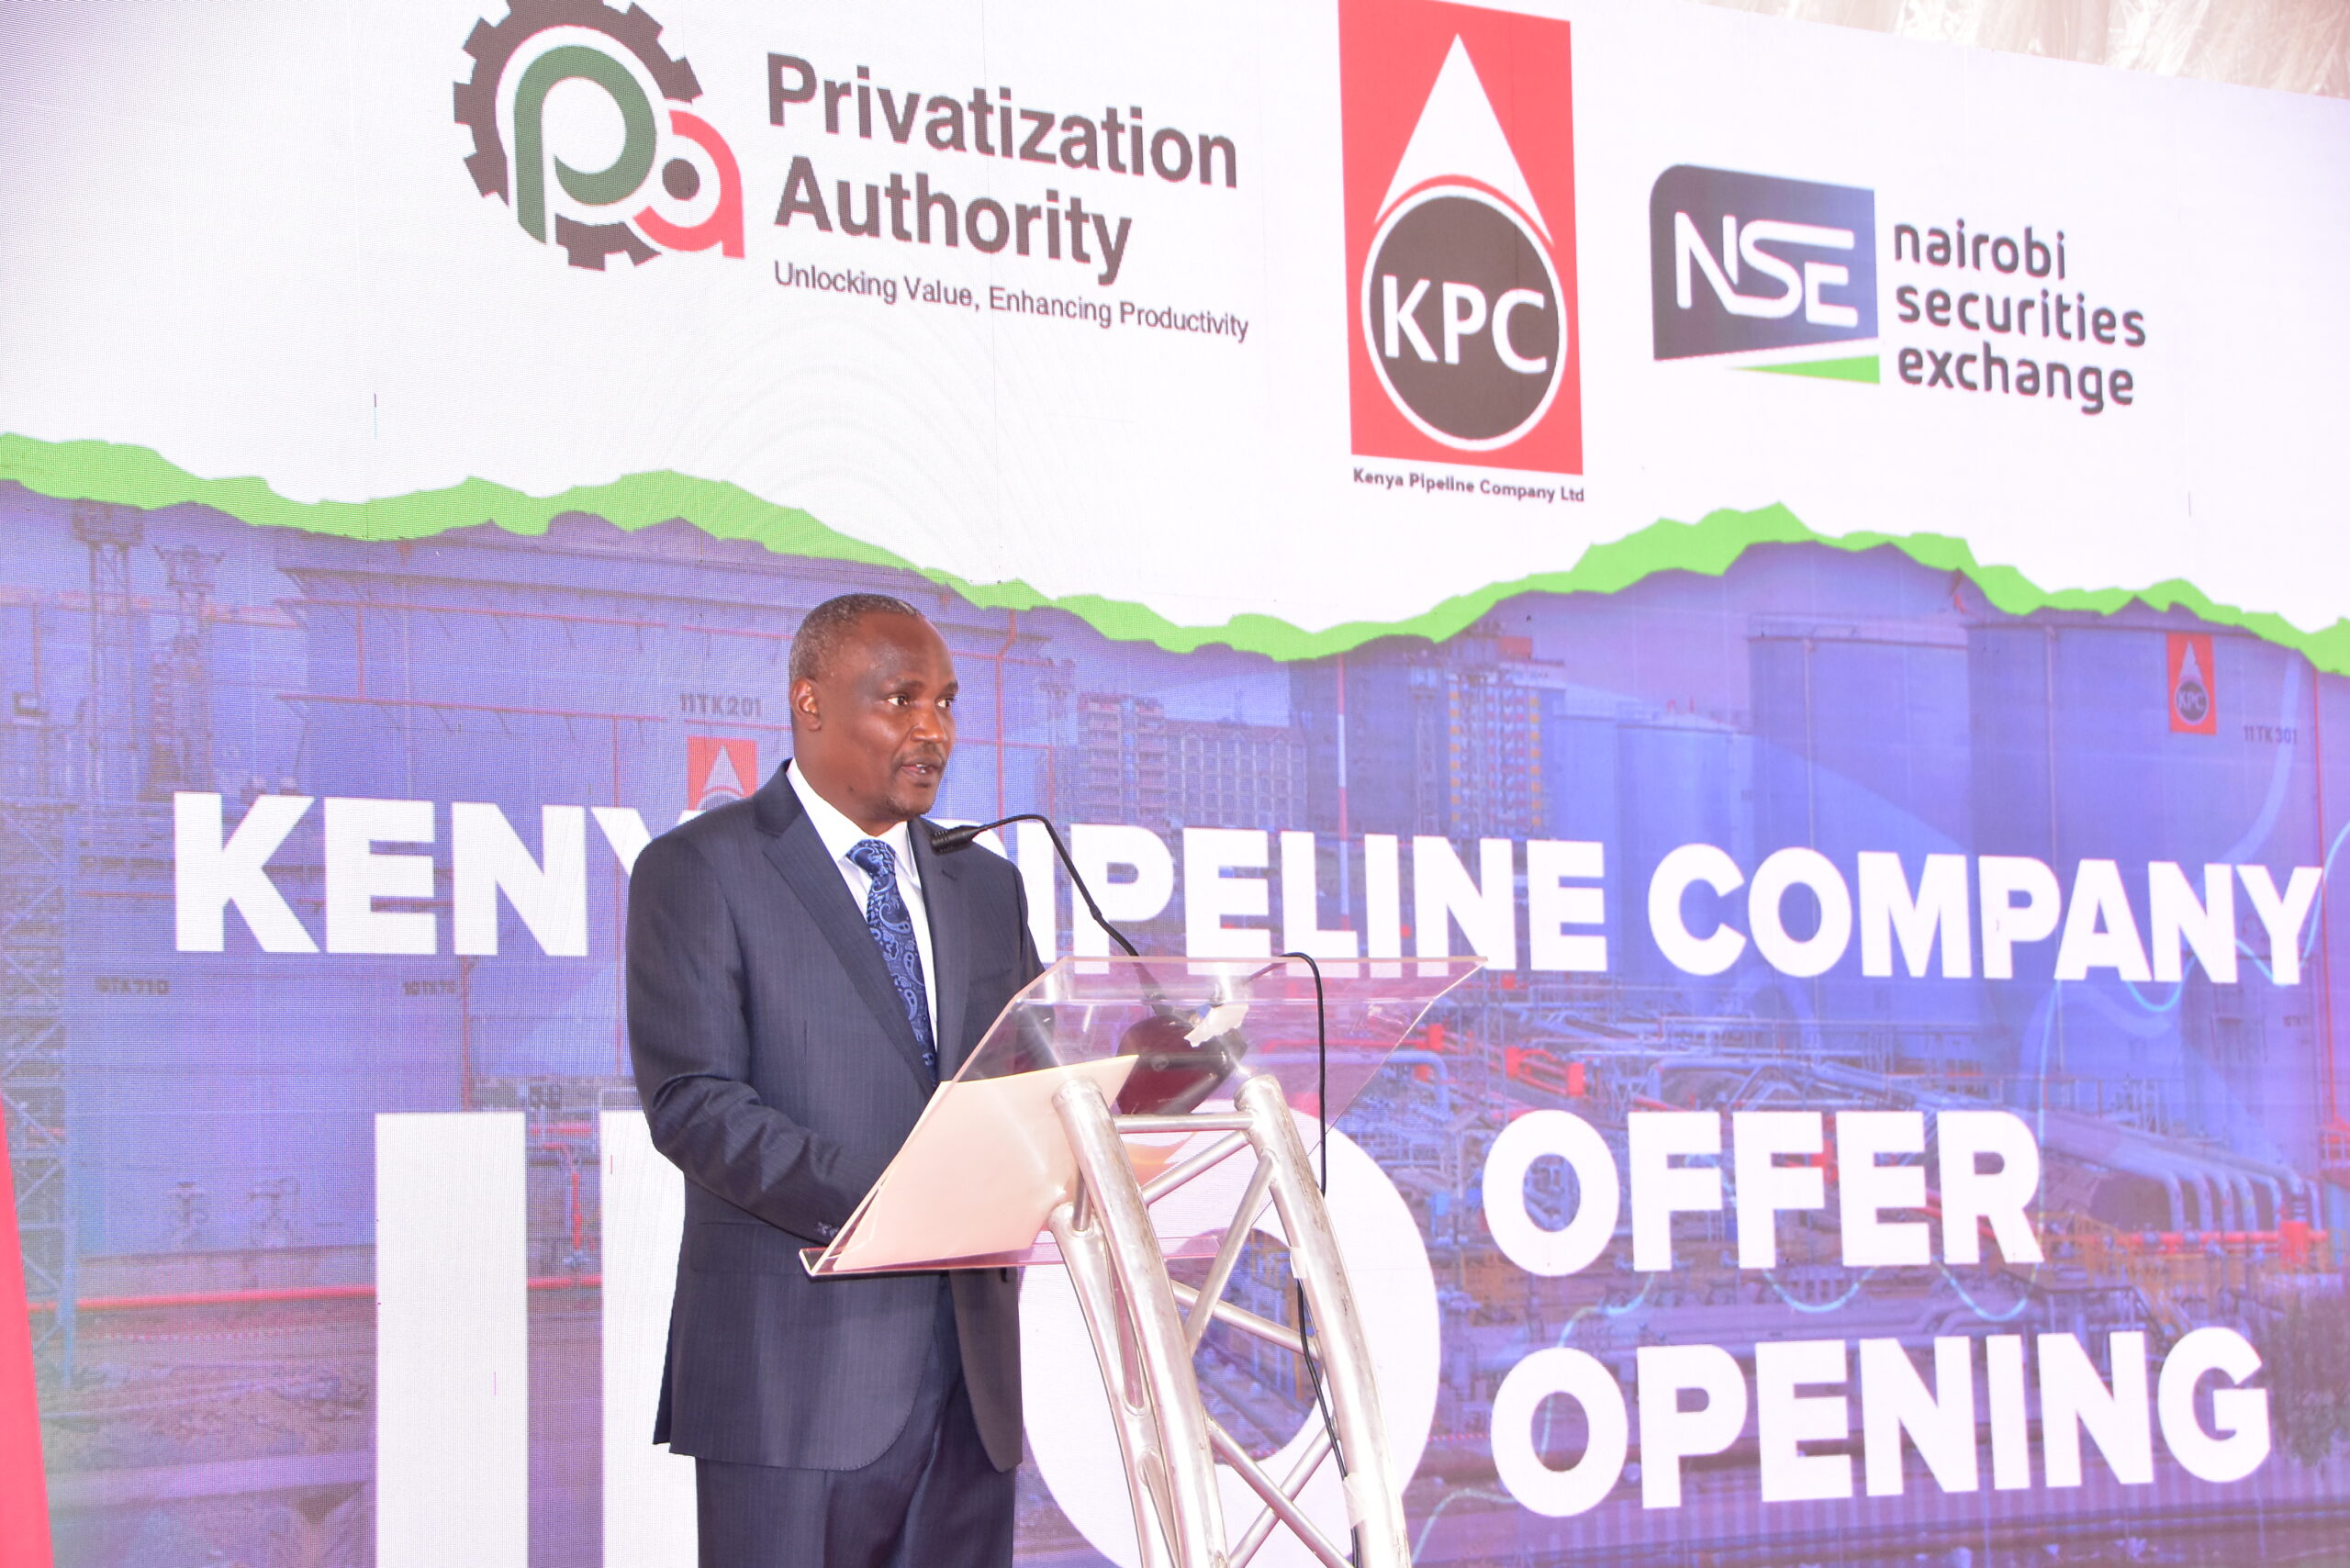
Kenya’s stock‑market narrative, long defined by few new listings and a preference for private capital, is showing signs of change as recent activity on the Nairobi Securities Exchange gains attention.
The March 2026 listing of Kenya Pipeline Company attracted demand that exceeded the 106.3 billion shilling offer, highlighting strong investor appetite for a large, recognizable Kenyan enterprise.
In October, Quickmart launched a share offer that differs from a traditional IPO because it involves the sale of existing shareholder holdings rather than fresh capital for the retailer, yet it expands public ownership and market depth.
The ALP Industrial Real Estate Investment Trust demonstrates that the exchange can also host income‑producing property assets, adding another layer of investment choice beyond equity listings.
Analysts argue that a mature capital market should do more than host occasional blockbuster IPOs; it must link diverse businesses with investors seeking varied exposure, liquidity and returns.
Companies now face multiple financing routes: bank loans, private‑equity deals, conventional IPOs, REITs, corporate bonds or SPACs, each with distinct costs, disclosure demands and exit options.
The key question remains whether Kenyan firms have enough credible alternatives to select the structure that best fits their growth plans.
Beyond raising capital, the market’s health depends on liquidity, price discovery, broad investor participation and reliable exit mechanisms, especially given Kenya’s sizable domestic savings pool.
Stakeholders see the current momentum as an opportunity to convert renewed attention into lasting market depth, moving beyond the sheer number of IPOs toward a versatile capital‑market ecosystem.


Comments