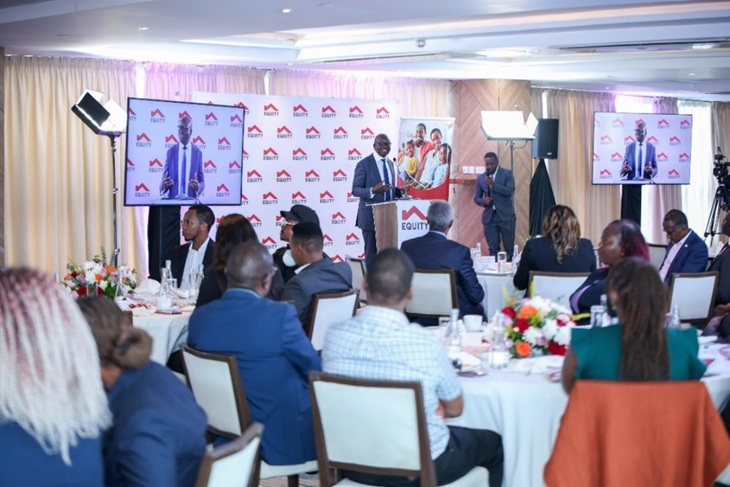
The Kenya Bankers Association’s Director of Technical Services, Fidel Muia, told participants at the Cyber Risk Awareness Forum in Nairobi that the rapid uptake of digital tools has heightened exposure for both large corporates and SMEs, prompting a push for cyber risk insurance.
Muia highlighted a surge in local cyber incidents, noting that the Communications Authority of Kenya logged 3.37 billion threat events in the first quarter of 2026 – roughly 433 attacks per second.
According to Interpol’s 2026 Global Financial Fraud Threat Assessment, AI‑enabled scams are now 4.5 times more profitable than traditional fraud, driven by a growing Fraud‑as‑a‑Service market that supplies ready‑made deep‑fake and phishing tools to low‑skill criminals.
A PwC Forensics Digest released in September 2026 identified four gaps – speed, skills, visibility and trust – that organisations face when confronting AI‑powered attacks, including deepfakes that bypass conventional identity checks.
Equity Bank Kenya Managing Director Moses Nyabanda warned that ransomware and AI‑driven cybercrime now threaten individuals, businesses and government bodies, stressing that no enterprise is immune in a fully digital transaction environment.
Forum participants agreed that cybersecurity must move from a back‑office IT issue to a boardroom agenda, with specialised cyber insurance positioned as a mandatory “last line of defence” to cover data breaches, network failures and business interruptions.
Risk experts at the event described cyber policies as essential for offsetting the financial fallout of breaches, including system recovery costs, regulatory fines and losses from compromised customer data.
They advocated a three‑pronged resilience strategy: intelligent threat detection, disciplined human verification and the financial safety net provided by cyber insurance.


Comments