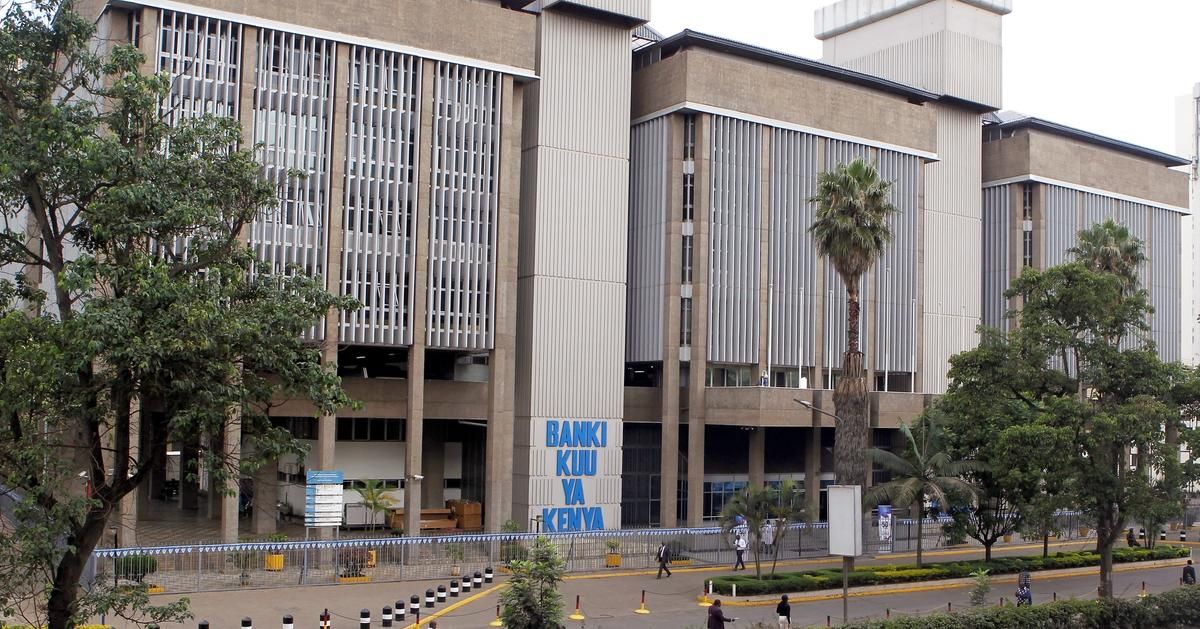
In the latest The Banker Top 1000 ranking, none of Kenya’s banks appear among Africa’s ten highest‑movers, a drop from four Kenyan lenders in the previous edition.
The change follows the Kenyan shilling’s move from a sharp 2024 appreciation to a narrow band of roughly KSh129.00‑KSh129.92 per US dollar, removing the currency‑driven boost that had inflated dollar‑denominated capital and asset figures.
The Banker notes that when the shilling stabilises, the extra dollar‑value growth disappears, leaving Kenyan banks more exposed to the underlying performance of their balance sheets relative to peers whose currencies have strengthened or who have raised fresh capital.
All Kenyan lenders except Standard Chartered Bank Kenya reported increases in Tier 1 capital, total assets and pre‑tax profit for the period covered by the ranking.
KCB Group and Equity Group each fell two places in the African list, landing at 15th and 17th respectively, while their global positions improved to 542nd and 573rd.
KCB’s first‑half 2026 results showed total assets of KSh2.299 trillion (up 16.8%), deposits of KSh1.711 trillion (up 15.1%) and gross loans rising 14.2%, with gross non‑performing loans falling by KSh17.3 billion.
Equity Group reported first‑half profit after tax of KSh45.5 billion, deposits of KSh1.59 trillion (up 21%) and total assets of KSh2.16 trillion, reflecting strong loan‑book expansion.
Across the Nairobi Securities Exchange, nine of the eleven listed banks that released results posted a combined net profit of KSh144.9 billion, a 16.9% increase year‑on‑year, helped by lower funding costs and better asset quality.
Regional competition and foreign interest
Banks in Nigeria, Egypt and Morocco moved up in the ranking as their local currencies strengthened and many raised additional equity, notably after Nigeria’s central bank tightened capital requirements in March 2024.
Nigerian lenders such as Stanbic IBTC, Standard Chartered Nigeria and Access Holdings saw Tier 1 capital surge by 36% in dollar terms, a mix of capital injections and currency effects.
Fourteen of Africa’s top‑25 banks have a presence in Kenya, with South African groups dominant; Standard Bank, Absa and Nedbank all operate locally.
Nedbank’s October 2026 acquisition of a 66% stake in NCBA gives it an established Kenyan platform and broader East African reach, illustrating how cross‑border deals reshape market dynamics.


Comments