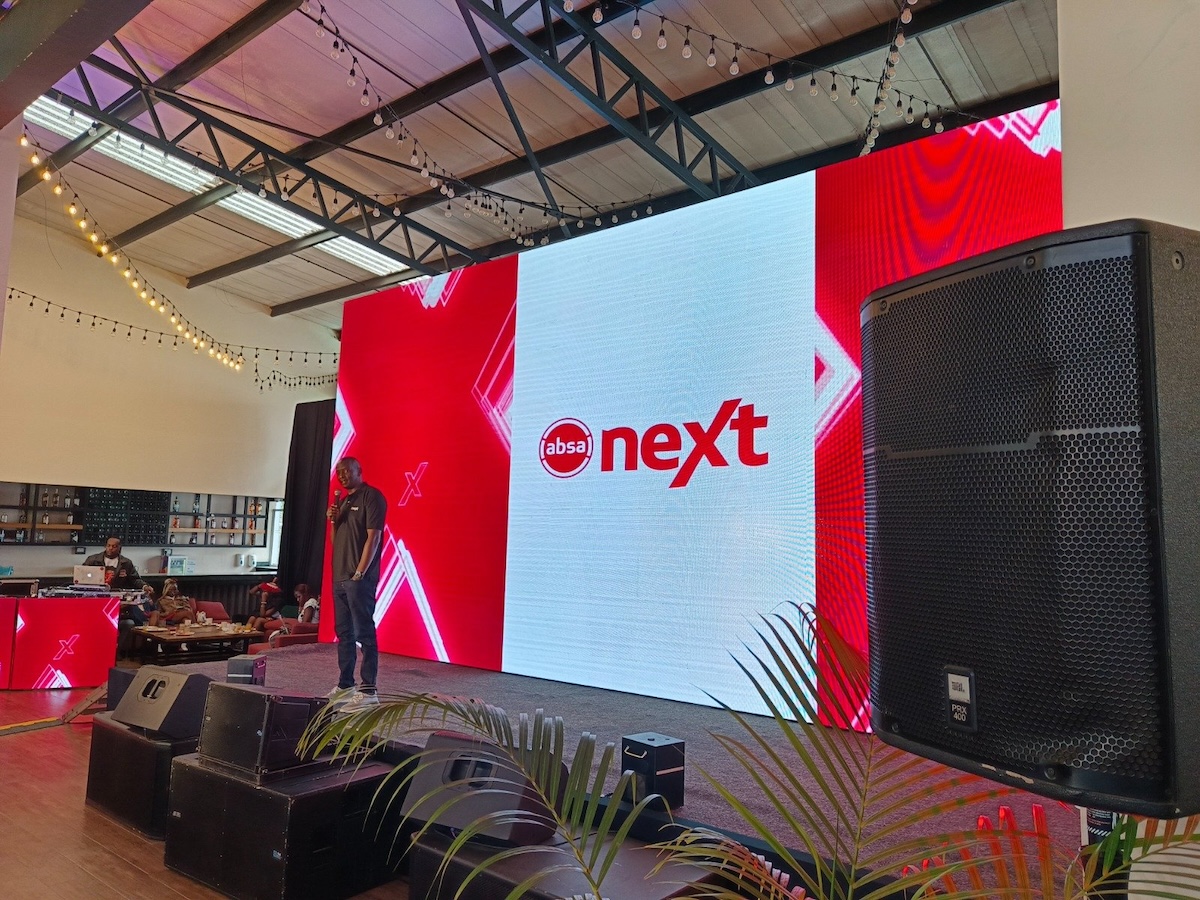
Absa Next is a digital finance platform that brings banking, payments, credit, savings, investments and business finance together in one mobile interface.
The app is available to both Absa customers and people without an Absa account, allowing anyone to access the suite of services after downloading the application.
At launch users can borrow between KSh500 and KSh1 million, save at rates up to 7 % and access investment products that advertise potential returns of up to 16 %, subject to product availability.
Features also include bill‑splitting, goal‑based savings, Chama and Harambee group management, and a business wallet that consolidates collections, payments and credit for small enterprises.
Customers can link Visa cards and accounts from other banks, giving a consolidated view of financial activity across institutions.
Absa aims to acquire one million users in the first year, using the Kenyan market as a testbed for a broader group‑wide digital strategy.
Why Absa is launching a new platform
Absa has been spending between KSh2 billion and KSh3 billion annually on technology, with about 94 % of customer transactions already occurring outside physical branches by 2025.
The bank digitised 71 % of its customer processes, positioning it to move beyond a conventional mobile‑banking front end toward a broader digital financial hub.
Absa’s digital team, led by head of digital banking Steve Omamo, involved more than 50 customers, entrepreneurs and creators in co‑creation workshops to shape the platform around the themes of convenience and progress.
Sitoyo Lopokoiyit, who joined Absa after leading M‑PESA Africa, is steering the launch as part of a group‑wide push to embed financial services where customers already spend time.
Future steps and open questions
Absa Next will initially coexist with the bank’s existing mobile app and the Timiza service while the bank monitors usage patterns to decide whether the three digital propositions will be merged or kept separate.
The bank plans to iterate the platform based on customer feedback, with further updates expected as usage data accumulates.
Success will be measured not only by the one‑million‑user target but also by transaction frequency, volume of funds moved, adoption of SME tools and the extent to which non‑Absa users make the app a primary financial hub.



Comments